

Residential Property Development Loans for Your Next Project
At BLG, we have provided over £900 million in residential development finance for property developers and housebuilders across England, Wales and Scotland. Projects range from a handful of high-value detached homes to apartment schemes of a hundred units or more. Loans run from £1 million to £15 million.
You’ll be working with us directly as the lender. Your dedicated BDM will take your scheme from first conversation to final drawdown, and our own credit team makes the decision, with no introducer fee when you come to us direct.
Tell Us About Your Scheme
What is Residential Development Finance?
Residential development finance is a short-term loan that funds the purchase of a site and the cost of building new homes on it, repaid when the homes are sold or refinanced. Build costs are released in stages as work is completed and checked, rather than paid out as one lump sum.
At BLG, residential development is the core of what we do. We have lent to developers since 2003, and we fund all types of builds (standard and non-standard) including:
- New build houses, from small schemes of high-value detached homes to estates of family housing
- Apartment blocks and mixed tenure schemes
- Conversions of existing buildings into flats or houses
- Mixed-use schemes where residential is the main element
Why Developers Choose BLG for Residential Property Loans
✔ We lend our own funds and make our own credit decisions
✔ First charge security, with a facility built around your programme
✔ Monthly site monitoring, so drawdowns keep pace with your build
✔ One named BDM from first call to repayment, through to any future schemes in your pipeline
Meet Your BDMs
When you contact BLG about a residential scheme, you speak to none of the people below. They will be your point of contact from start to finish.

Who Does BLG Work With?
We work with SME developers building residential schemes with a GDV that supports a loan of £1m to £15m. You can come to us directly, and we also work with brokers who introduce schemes on their clients’ behalf.
Who are are not the right fit for: Schemes needing a loan of less than £1,000,000, and projects outside of England, Wales and Scotland. See how we help in each situation.
Our Residential Finance Lending Criteria
We lend from £1million to £15million on residential schemes across England, Wales and Sctoland, for terms of up to 24 months.
| Loan size | £1m to £15m |
| Loan term | Up to 24 months |
| Senior leverage | Up to 70% of GDV, including interest |
| Stretch senior | Up to 85% of costs, 90% including rolled-up interest |
| Lower leverage | Available if you prefer to put more equity in |
| Interest | Can be rolled up, so no monthly payments during the build |
| Security | First change over the development site |
| Drawdowns | In stages, checked by monthly site monitoring |
| Scheme types | New-build houses and apartments, conversions, mixed-use with a residential majority |
| Unit values | No upper limit on individual unit value |
| Planning | Full planning in place, bridging available while planning is obtained |
| Exit | Sale of units or refinance onto a longer-term facility |
| Location | England, Wales and Scotland |
What We Look At When Assessing Your Residential Scheme
- The site, the planning consent and any conditions still to discharge
- Your build costs and programme, and whether they are realistic for the scheme
- Local sales evidence that support the GDV, including for high-value homes
- Your experience and that of your contractor and professional team
- Your exit i.e. who will buy the homes, or how the loan will be refinanced.
We do not publish rates, because every facility is priced on the scheme in front of us. Your BDM will set out terms once they understand your project.
Typical Funding Scenarios
Sitatuons developers bring to us, and how we fund them. These are all illustrative residential development loan scenarios (and importantly, is not an exhaustive list of schemes we have and will fund) showing how residential development finance is typically used. Speak to a BDM about your own project.
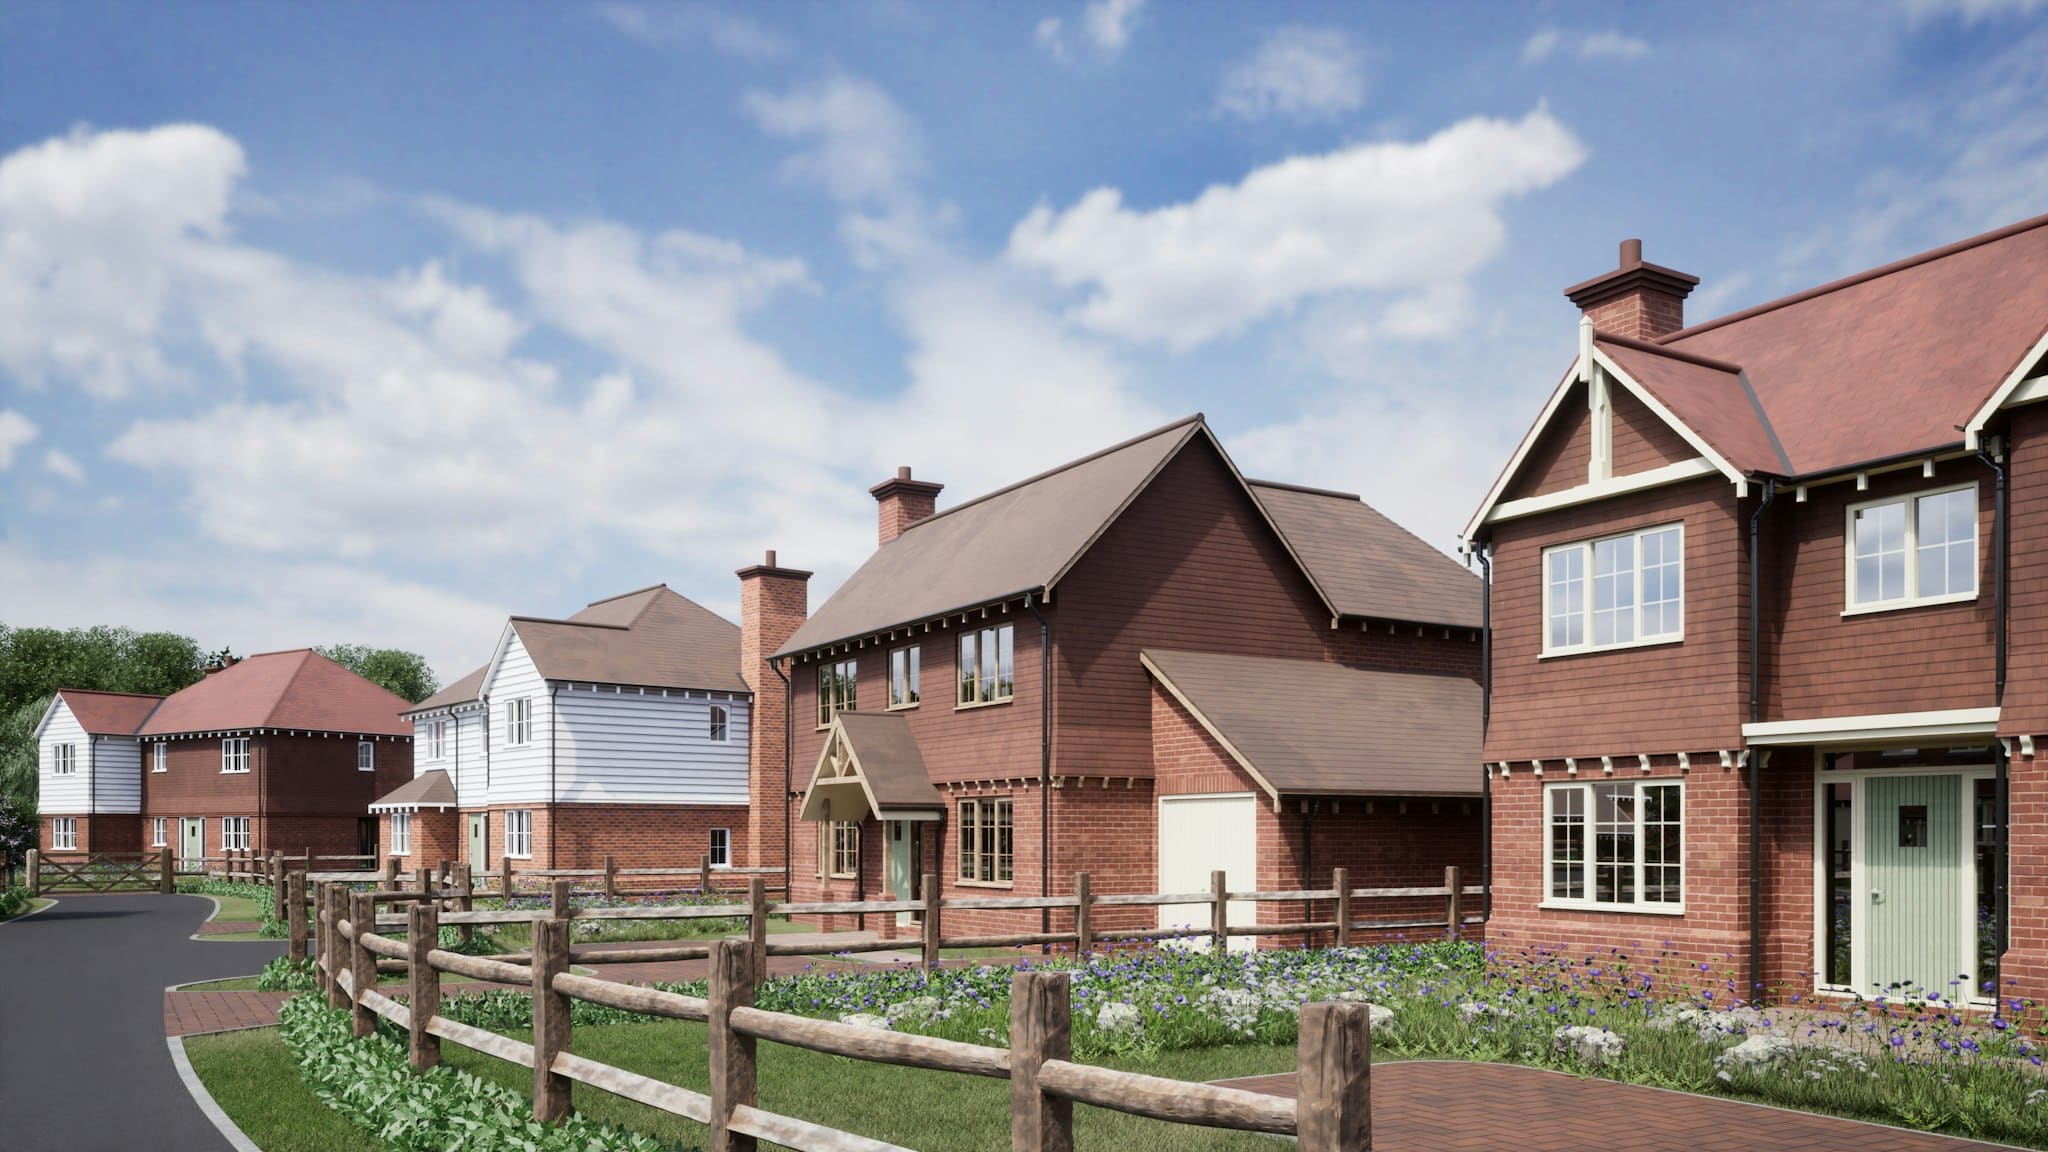
A small scheme of high-value detached homes
Scenario 1
You have planning for five detached, five-bedroom houses and want a specialist lender who understands premium homes.
We fund small schemes of high-value homes and assess them on local sales evidence for that property, not a standard house price.
A straightforward scheme at lower leverage
Scenario 2
You have planning, a proven contractor and plenty of equity, and you want a simple facility rather than maximum borrowing.
We structure lower-leverage senior facilities for experienced developers, with a BDM who keeps the process simple from heads of terms to completion.
Putting less of your own cash into your scheme
Scenario 3
Your appraisal works, but a standard senior loan leaves a gap you would otherwise fill with mezzanine finance from a second lender.
Our stretch senior facility funds up to 85% of costs (90% including rolled-up interest) in one loan, with one valuation and one legal process.
Securing a site before planning is granted
Scenario 4
You have found a site that suits residential development, but planning is still pending and a bank will not lend until consent is in place.
We are comfortable with planning-stage risk. Early stage bridging secures the site, then we refinance onto a development facility once planning is granted.
Your first scheme as a lead developer
Scenario 5
You have worked in construction or property for years, but this is the first scheme in your own name.
We lookat your full team, including your contractor, project manager and QS, and your BDM explains what we need from you at each stage.
Funding your next site while this one is on site
Scenario 6
You are mid-build and want to buy your next site without waiting for this scheme to sell out.
Because your BDM already knows your current schem, we can ssess the next one quickly and without starting from scratch.
Who are are not the right fit for: Schemes needing a loan of less than £1,000,000, and projects outside of England, Wales and Scotland.
BLG vs High-Street Banks
The main difference is who you deal with. One BDM manages your scheme from first call to repatment, backed by a credit team that only assesses development finance. At a high-street bank, development lending is often one product among many, run through a central credit process.
| | BLG | High-street banks (typically) |
| Your point of contact | One named BDM from enquiry to repayment | A relationship manager, with credit decisions made elsewhere in the bank |
| Who decides | Our own credit team, in-house | A central credit function |
| Focus | Development finance and bridging for developers only | Development lending alongside many other products |
| Planning-stage sites | Early stage bridging to buy before planning | Usually require planning to be in place |
| Pre-sales | Not required where sales evidence supports the GDV | Often required before committing |
| High-value homes | Assessed on local evidence for that type of home | May apply limits on individual unit values |
| Leverage | From lower leverage up to 90% of costs including rolled-up interest | Often lower leverage only |
| Your next scheme | Your BDM already known your track record | May mean a fresh application and process |
When a bank may suit you better: If you have substantial pre-sales, modest leverage and an established banking relationship, a high-street bank facility can be a sensible choice. We are happy to talk it through, even if the answer is that we are not the right fit.
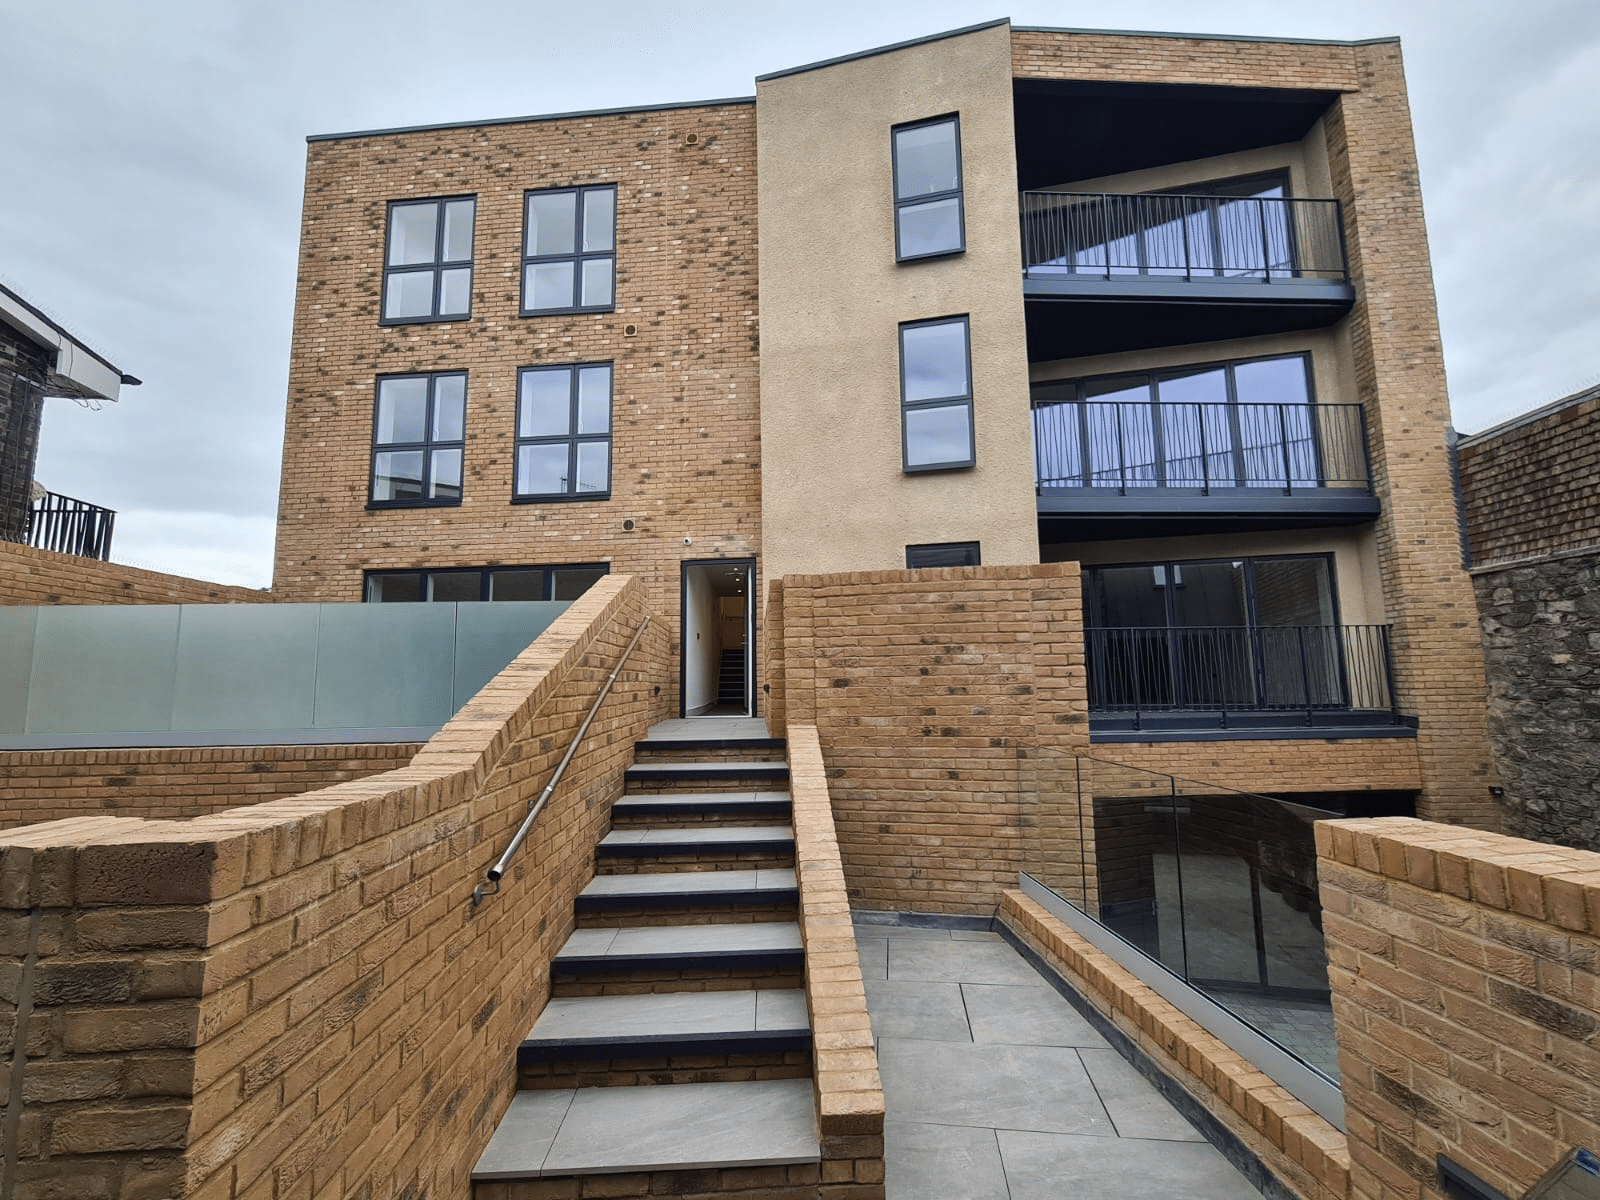
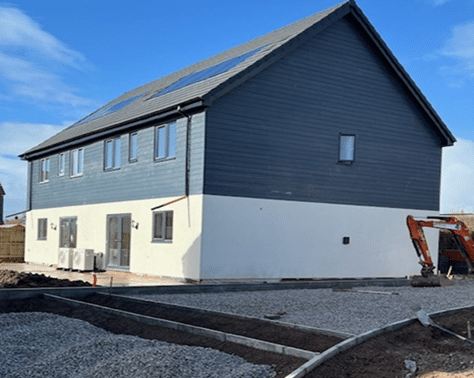
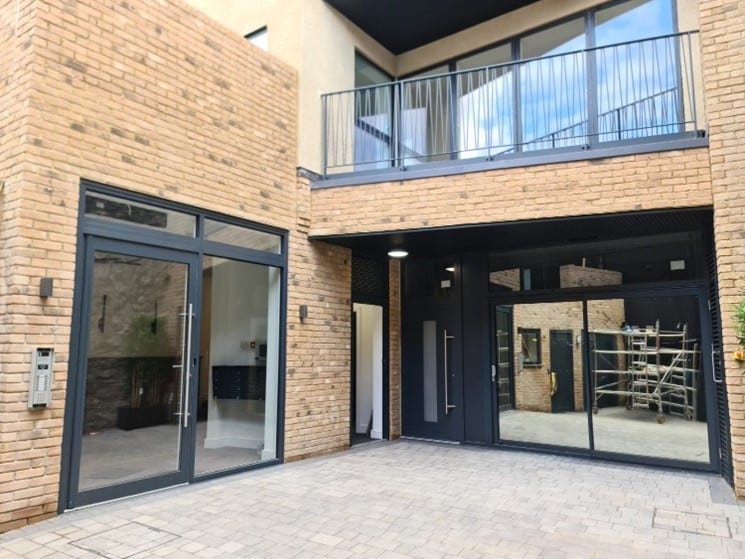
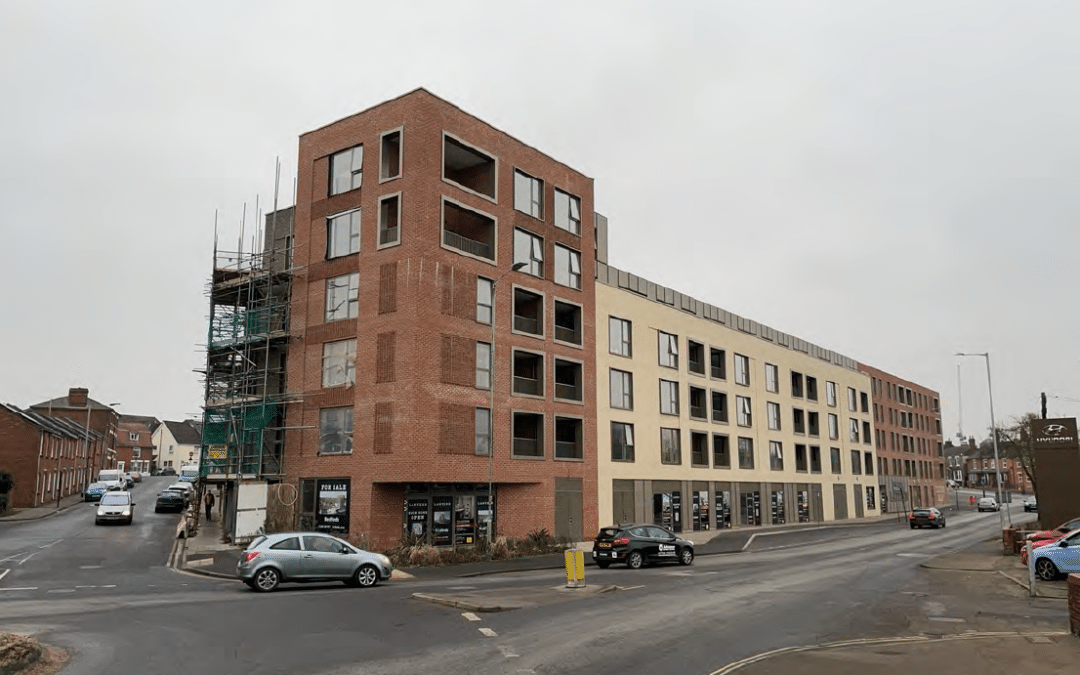
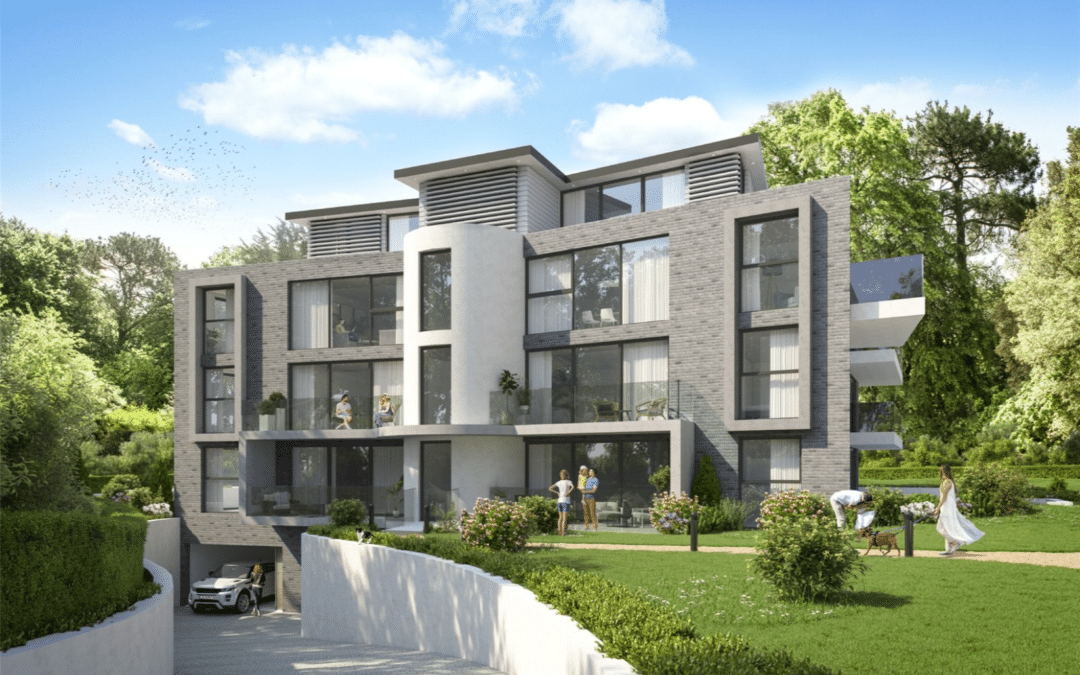
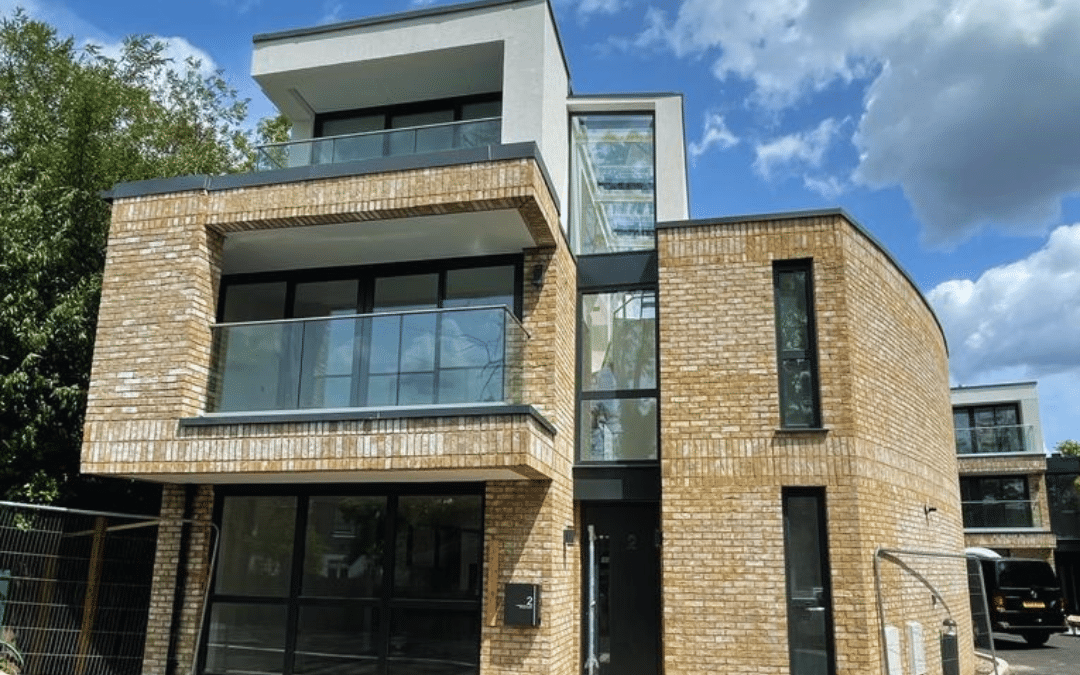
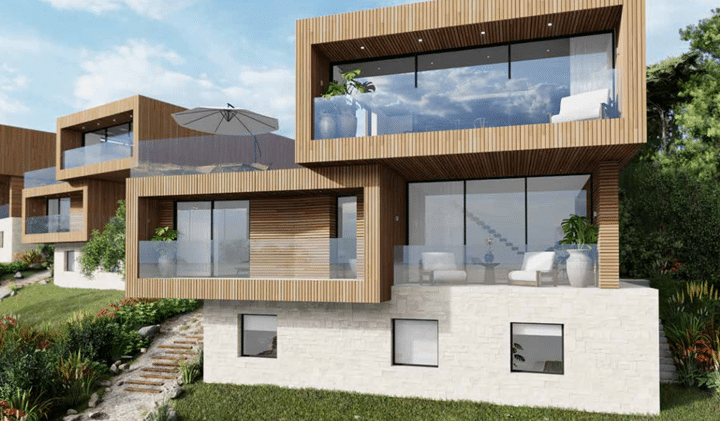
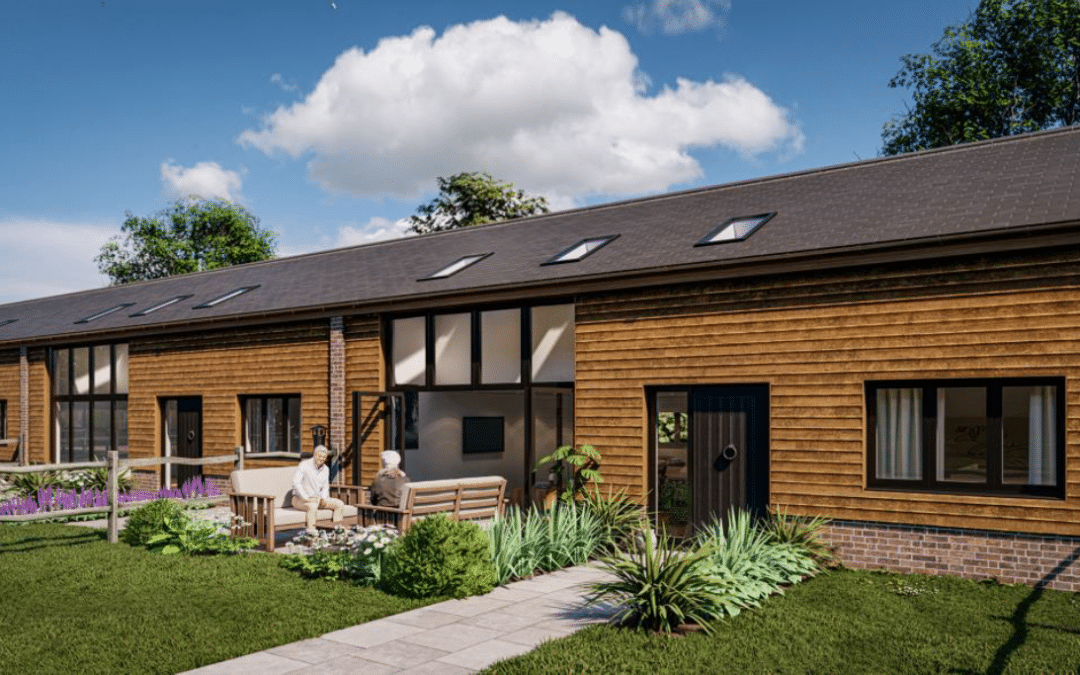
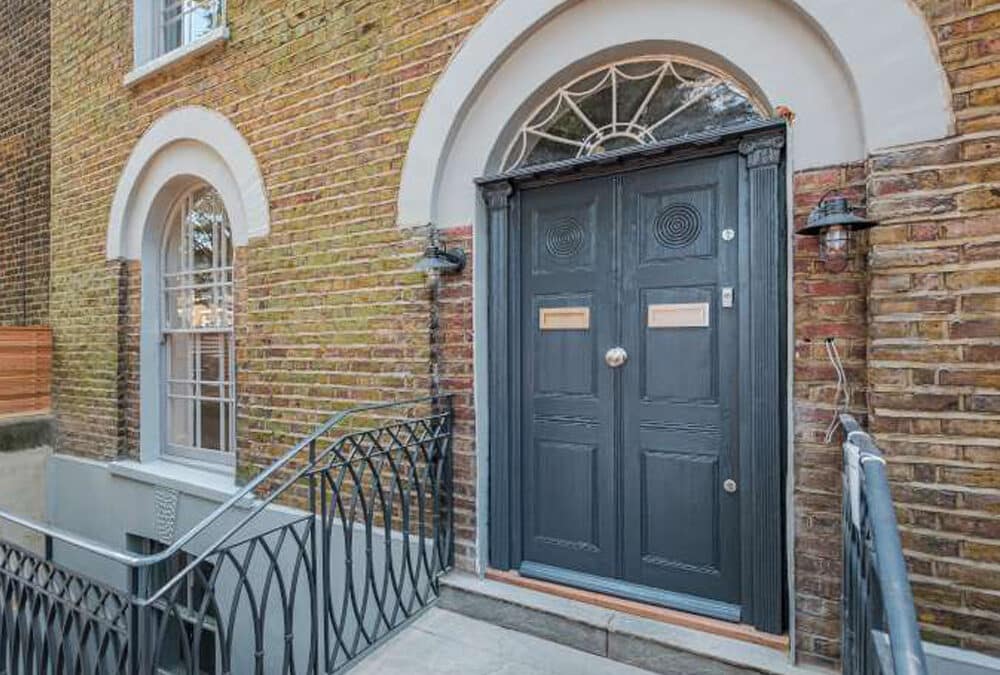
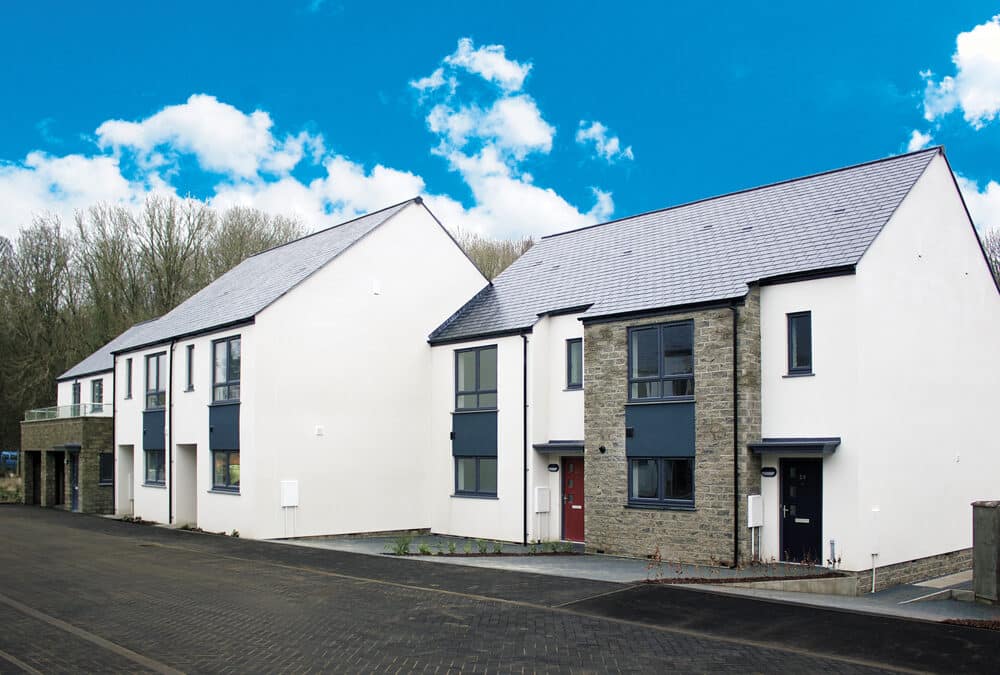
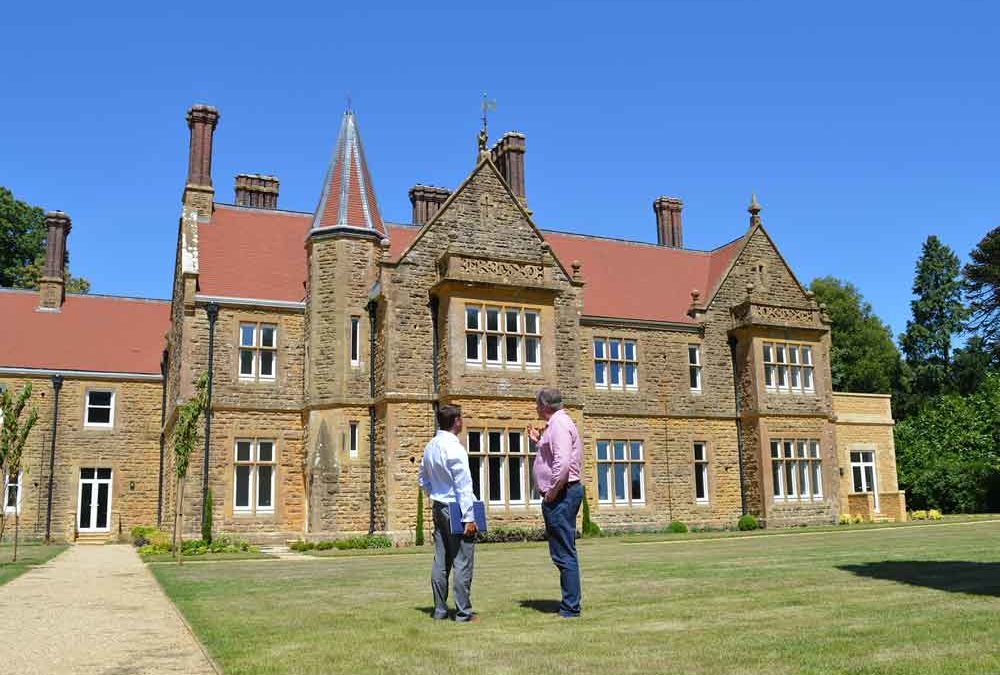
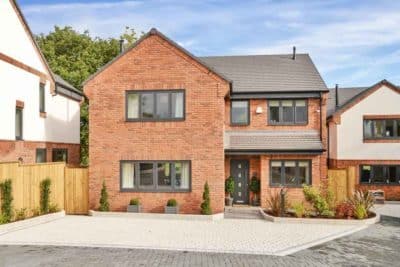
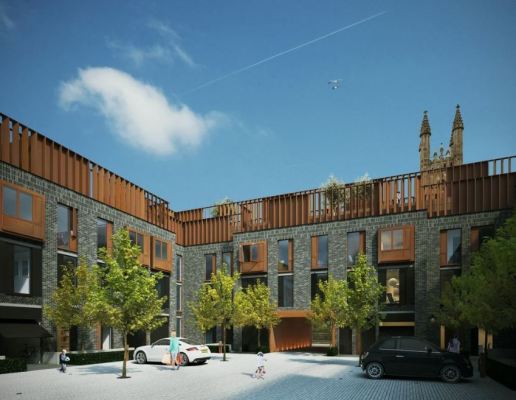
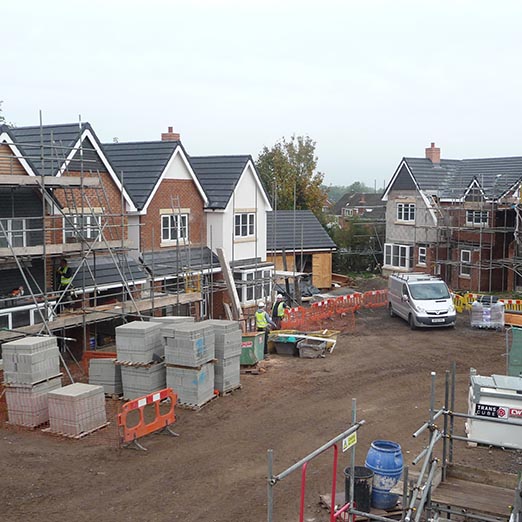
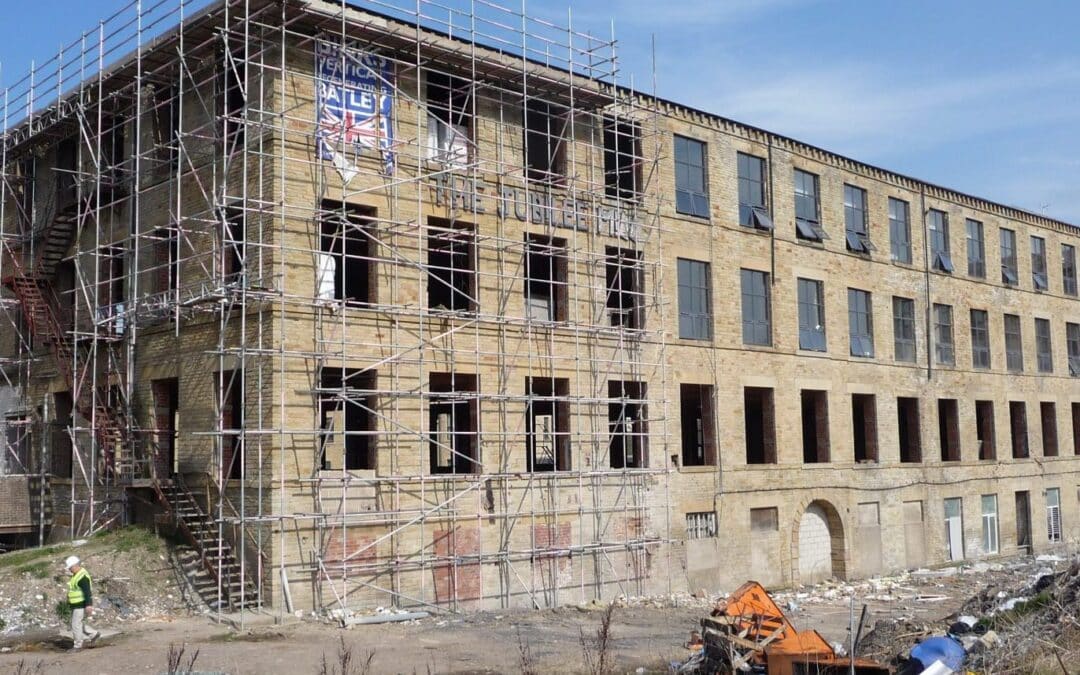
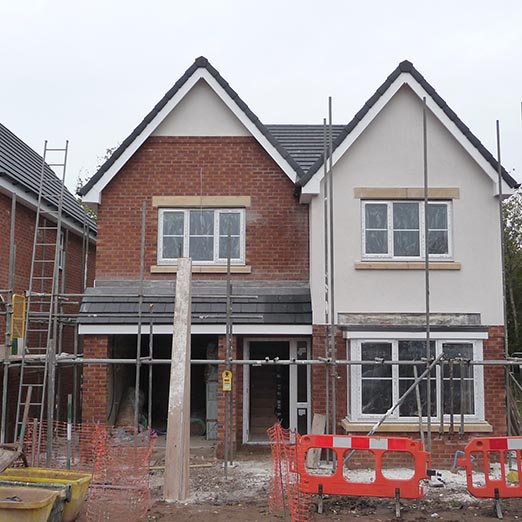
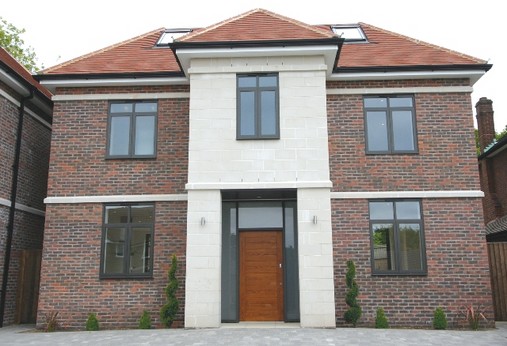
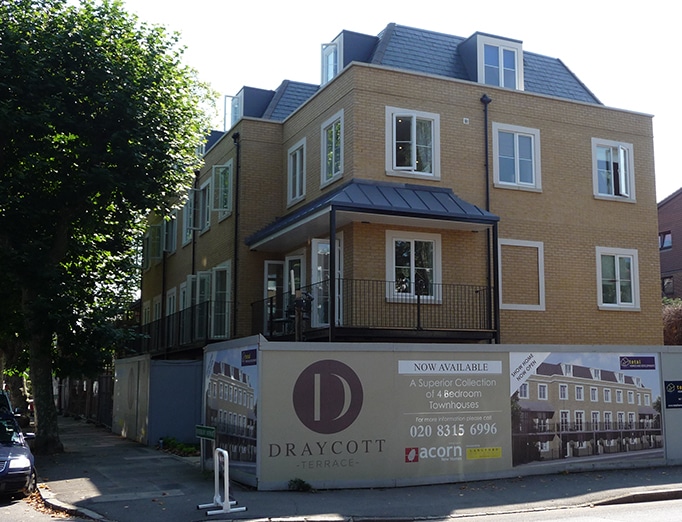
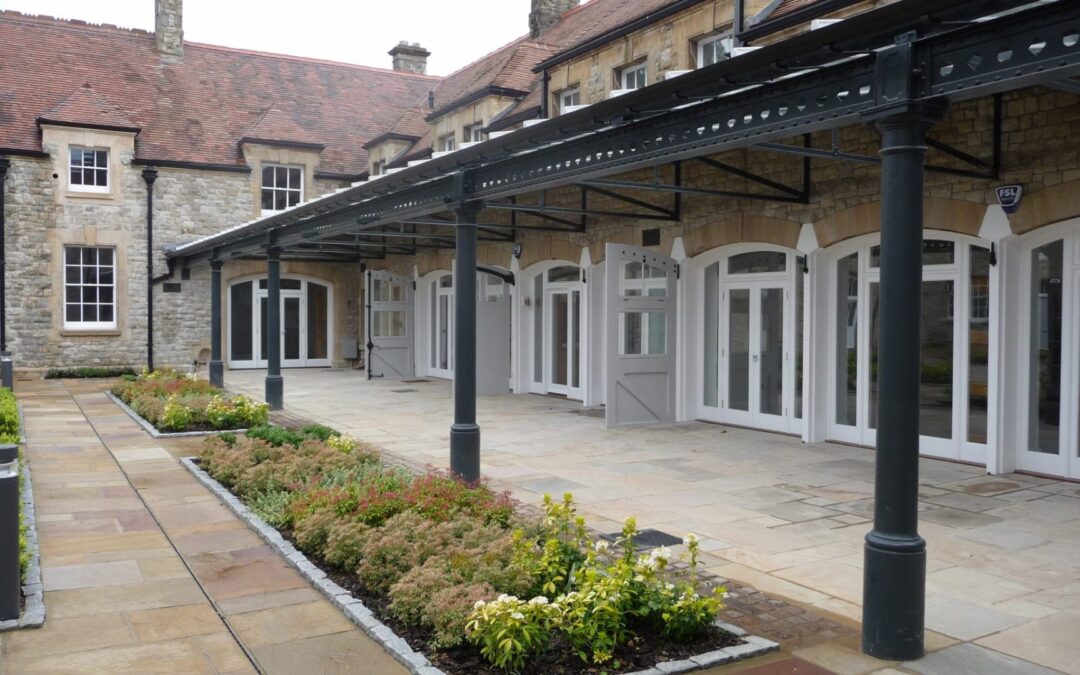
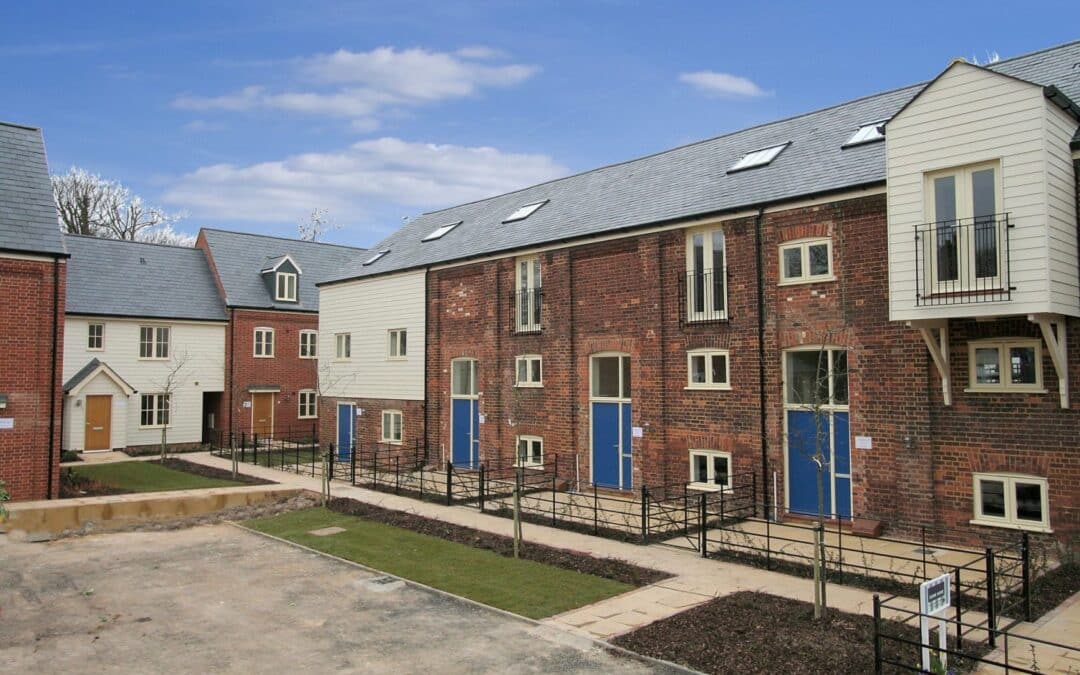
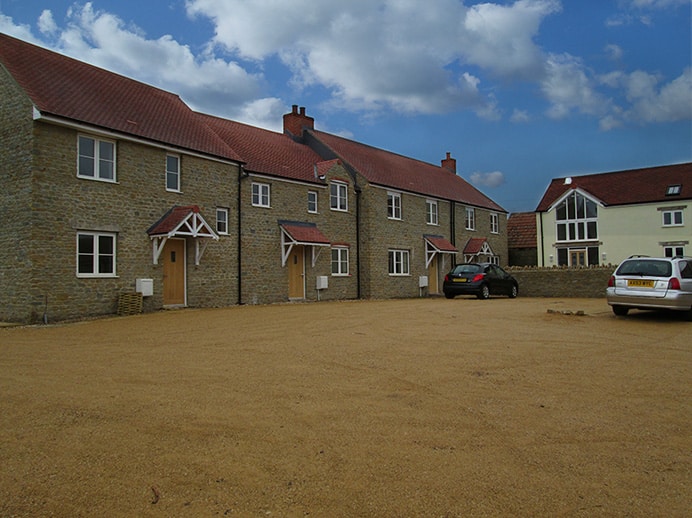
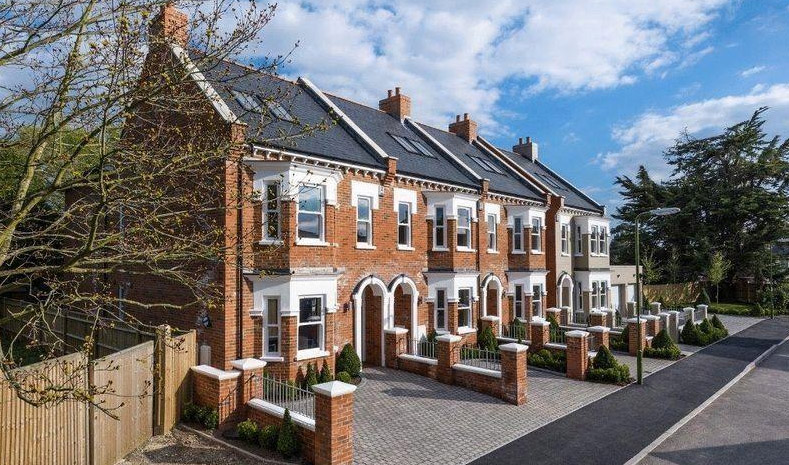
Residential Schemes We Have Funded
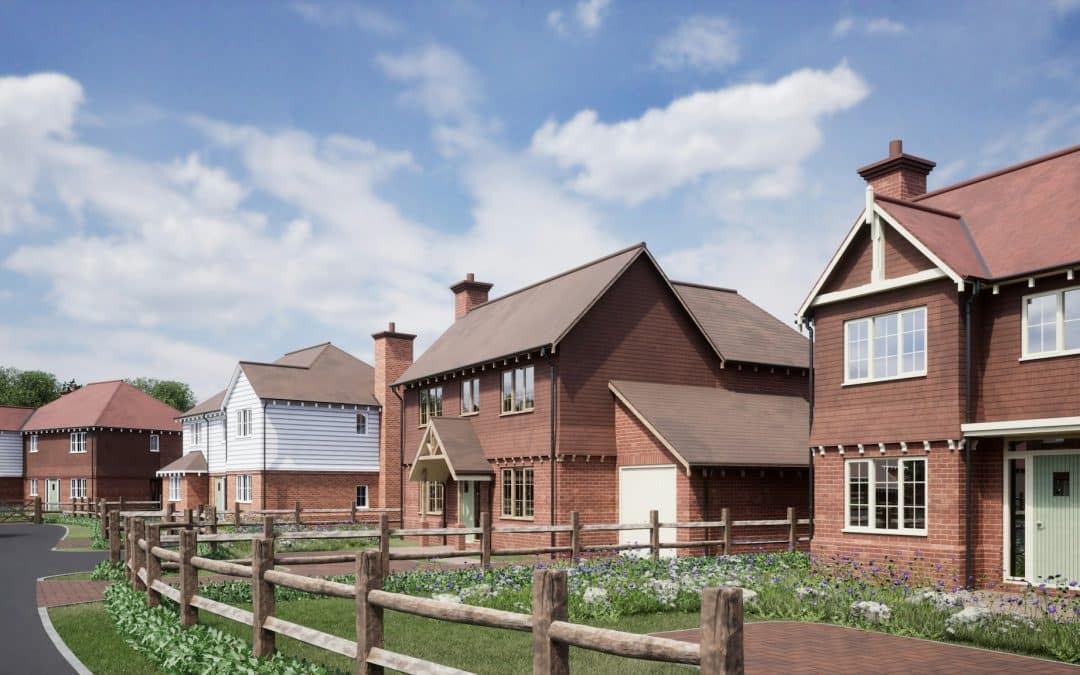
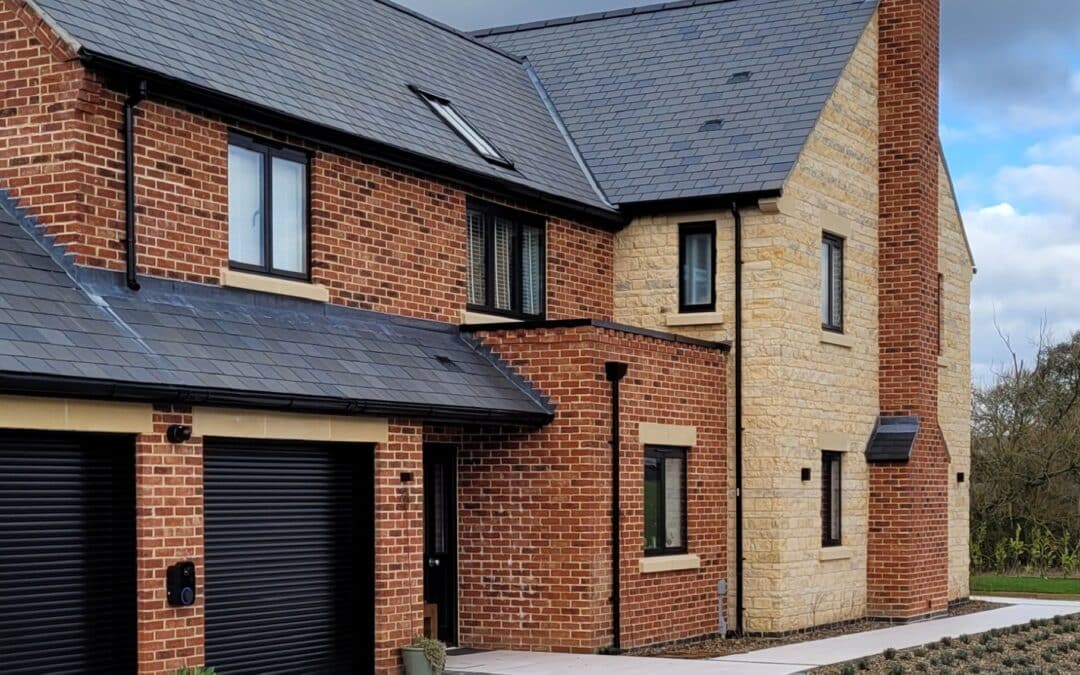

How Can You Speed Up Your Funding With BLG
The biggest factor in your timescale is usually how complete your information is at the start.
Have these ready before your first call with your BDM and you can speed up the funding approval process:
- Development appraisal: land, build costs, fees, finance and GVD
- Planning decision notice and outstanding conditions
- Build cost plan, ideally prepared or reviewed by a QS
- Local sales evidence supporting your GDV
- Developer CV with completed schemes and addresses
- Asset and liability statement
- Your planned exit: sale of the units or refinance
Straightforward schemes
More complex schemes
Residential Development Finance FAQs
What's the Difference Between Residential Property Finance and a Mortgage?
Residential development finance is a short-term funding solution used to purcahse land and fund the construction or conversion of residential property.